Featured Posts
Is My House Titled Correctly? Should I Quitclaim It to My Kids?
 Most homeowners can get an answer to that first question in about five minutes: pull out your property tax bill and check whose name — and which trust, if any — is listed as owner. If it matches your current estate plan, your title is likely in good shape. As for quitclaiming the house to a child now instead of through your estate plan, the short answer is usually not, or at least not without weighing the consequences a quick form doesn’t warn you about.
Estate planning attorney Heather Johnston brought these issues to our attention in a CFP® continuing education course about “title” — the legal right of ownership in a property, and how that right is documented. Get it wrong, and the ramifications can be serious.
The tax bill test
Technically, title to your home changes hands the moment a deed is validly signed and delivered — recording it with the county just puts the world on notice. But practically, the recorded deed is what you, your heirs, and any title company will actually rely on. If it isn’t right, or no longer matches your estate plan, that gap stays invisible until someone needs it to be right.
If your home is meant to be held in a living trust, the property tax bill, or your online account with the county recorder’s office, should show something like: [Your Name(s)], Trustee(s) of the [Trust Name], dated [date], or John Smith and/or Jane Smith, trustees of the Smith Family Trust dated 7/11/2010.
If you don’t have or want to use a trust, for whatever reason, it is still important to verify that the records reflect the current deed’s true owner(s) and their interest. In California, and 8 other states, a husband and wife should almost always own the property as “community property” according to Johnston.
On your tax bill, look for anything different than what you intend. If you see anything else — your name outright with no trust reference, an old name, a deceased spouse still listed, an ex-spouse, a trust name that doesn’t match your current plan — that’s your signal to dig further. It doesn’t mean something is broken, but it does mean it’s worth confirming rather than assuming.
The bigger risk: “Let’s just do a quick quitclaim”
According to Johnston, quitclaims are one of the worst ideas she sees implemented. The public seems determined to avoid attorney fees in favor of a five-minute form that can:
- Wipe out the heirs’ stepped-up cost basis had they inherited the property instead
- Trigger a property tax reassessment
- Count against your lifetime gift and estate tax exemption, and require a gift tax return
- Void your title insurance, if you have an owner’s policy — coverage generally follows the original owner, not a later transfer made by gift
- Cancel or raise your homeowner’s insurance
- Leave you personally liable on a mortgage you no longer control, and possibly trigger a due-on-sale clause forcing you to pay it off immediately
- Hand your house to a child’s creditor in a bankruptcy or lawsuit, a divorcing spouse in a settlement, or the wrong beneficiary entirely if that child dies before you and the house passes through their estate instead of yours
That last bullet covers two of what Johnston calls “the three Ds” — divorce and death. The third, disability, is easy to miss: if your child later becomes incapacitated and needs to qualify for means-tested government benefits, owning the house outright can work against them, or leave a conservator managing an asset you never intended for that purpose. Together, these are the risks families think about least and regret most. Once your name comes off the deed, you no longer control what happens to that asset if your child’s life goes sideways.
None of this depends on the deed being recorded. Signing and delivering it is enough to trigger these consequences — a quitclaim sitting unfiled in a kitchen drawer has still changed who owns the property, whether the county ever finds out or not.
Gifting property to a child may be the right move, but don’t do it without qualified advice. An attorney can lay out your legal rights while an Enduring Wealth Advisor® can help you understand the potential financial consequences.
A three-question mini-audit
When you’re reviewing your financial situation, especially in light of estate planning questions, ask three questions:
- Is there a deed – recorded or not – that reflects who actually owns this property today?
- Has anything changed since that deed was signed — a refinance, a name change, a move in or out of a trust?
- Would a transfer trigger a property tax reassessment, gift tax reporting, a basis adjustment, or a title/homeowner’s insurance problem?
If any answer gives you pause, that’s a phone call to an estate planning attorney.
Where we fit in
As Certified Financial Planner® professionals, we’ll incorporate your real estate into your broader financial and estate plans. We’ll work to align all your assets (and liabilities) with the goals you want to pursue, and we’ll coordinate that work with your tax and legal professionals to help you understand the consequences of any decisions you make.
Give us a call if that’s the kind of relationship you want with your financial advisor.
How one Couple gets the most out of Social Security
by Ralph Bender, MBA, CFP®
Randy loves the business he’s created. It was very difficult getting started, with no capital, three young kids. But the family rallied around him, helped him find good clients, and they survived. The longer he works in the business, the easier it gets to attract business…
Four Ways to Handle Your Future Long-Term Care Expenses
by Ralph Bender, MBA, CFP®
Half of us will need help with activities like bathing, dressing or eating sometime in our futures; the rest of us will die before needing such Long Term Care (LTC). With at least a 50% chance of needing LTC, it is important to have a plan for obtaining the care before you are most vulnerable…
Featured Market Volatility
Investing With Tariffs In Mind
by Ralph Bender, MBA, CFP®
Tariffs—taxes imposed on imported goods—have become an essential factor for investors to consider. They are typically used to protect domestic industries from foreign competition by increasing the costs of imported goods…
Teetertotter Market or Wall of Worry?
by Ralph Bender, MBA, CFP®
GrandpaLand is a swing, trampoline, hammock, and a teetertotter in the shaded corner of our back yard. On Thursdays, the “littles,” as we call the grandkids under seven, spend the day with Grandma, while their respective parents get some work done…
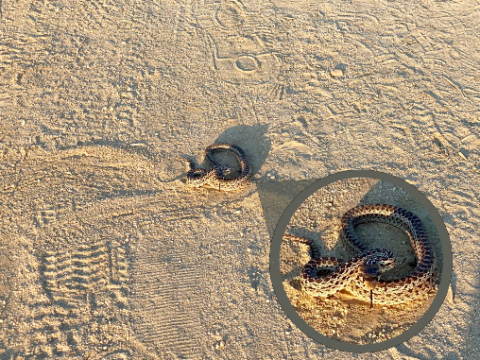
Running Money® On the Trail – Don’t Get Bit
by Ralph Bender, MBA, CFP®
It was a little guy, about a foot long, just stretched out across the main trail. I was two steps beyond him before stopping, realizing it’s the first I’ve seen this season. Experienced runners develop a “sixth sense” about their footfalls…
Featured Financial Planning
Is My House Titled Correctly? Should I Quitclaim It to My Kids?
by Ralph Bender, MBA, CFP®
Most homeowners can get an answer to that first question in about five minutes: pull out your property tax bill and check whose name — and which trust, if any — is listed as owner…
You’re Too Young to Think About Dying — That’s Exactly the Problem
by Ralph Bender, MBA, CFP®
“Tariffs—taxes imposed on imported goods—have become an essential factor for investors to consider. They are typically used to protect domestic industries from foreign competition by increasing the costs of imported goods…
Three Benefits, One Decision: Should My Spouse Claim SS Early While Still Working?
by Ralph Bender, MBA, CFP®
A client recently asked a question I hear regularly. The names have been changed, but the situation is common enough that the answer is worth sharing publicly…
Featured Lifestyle
Book Review: The Man Who Knew
Review by Ralph Bender, MBA, CFP®
I thought I knew Alan Greenspan. After all, I lived through his entire tenure at the Fed, watched him testify before Congress, and experienced the economic cycles he helped shape. Turns out, I didn’t know him nearly as well as I thought. Sebastian Mallaby’s “The Man Who Knew” reveals a far more complex and fascinating figure than the measured, almost robotic Fed chairman who appeared on our television screens….
Recipe: Mark’s Version of Pioneer Woman’s Potato Soup
by Mark R Tracy, MBA, CFP®
½ to 1 lb. of raw bacon, diced
1 cup of diced onions
1 cup of diced carrots…
Fitness: The Age-Proof Brain
Review by Ralph Bender, MBA, CFP®
In “The Age-Proof Brain,” Marc Milstein provides an easy-reading yet highly informative guide to maintaining a healthy and sharp mind throughout life. Milstein, a neuroscientist, skillfully combines the latest scientific research with practical advice, creating a comprehensive guide to cognitive well-being…
Most Recent
Is My House Titled Correctly? Should I Quitclaim It to My Kids?
by Ralph Bender, MBA, CFP®
Most homeowners can get an answer to that first question in about five minutes: pull out your property tax bill and check whose name — and which trust, if any — is listed as owner…
Year-End Planning for Retirees
by Mark R Tracy, MBA, CFP®
As we approach the coming year, let’s look at year-end planning for your finances…
TALKING TO YOUR CHILDREN ABOUT INHERITANCE – Checklist
by Mark R Tracy, MBA, CFP®
If you feel uneasy chatting with your kids or grandkids about money, trust me, you’re not alone. Many parents find discussing inheritance with their children to be quite a challenge…
Blog Search
Get Our Newsletter
Schedule A Call
Securities are offered through LPL Financial, Member FINRA / SIPC. Investment advice offered through Enduring Wealth Advisors®, LLC, a registered investment advisor. Enduring Wealth Advisors®, LLC and Enduring Wealth, Inc are separate entities from LPL Financial.
The LPL registered representatives of Enduring Wealth Advisors® may only discuss securities or transact business with persons who are residents of AR, AZ, CA, CO, ID, KS, KY, LA, MN, NH, NM, NV, OH, OK, OR, PA, SC, SD, TX, UT, VA, WA, WV.
No information provided on this site is intended to constitute an offer to sell or a solicitation of an offer to buy shares of any security, nor shall any security be offered or sold to any person in any jurisdiction in which such offer, solicitation, purchase, or sale would be unlawful under securities laws of such jurisdiction.
EnduringWealth.com and Enduring Wealth Advisors® its content, links, and excerpts may be used with clear credit and attribution. Unauthorized use is prohibited.